
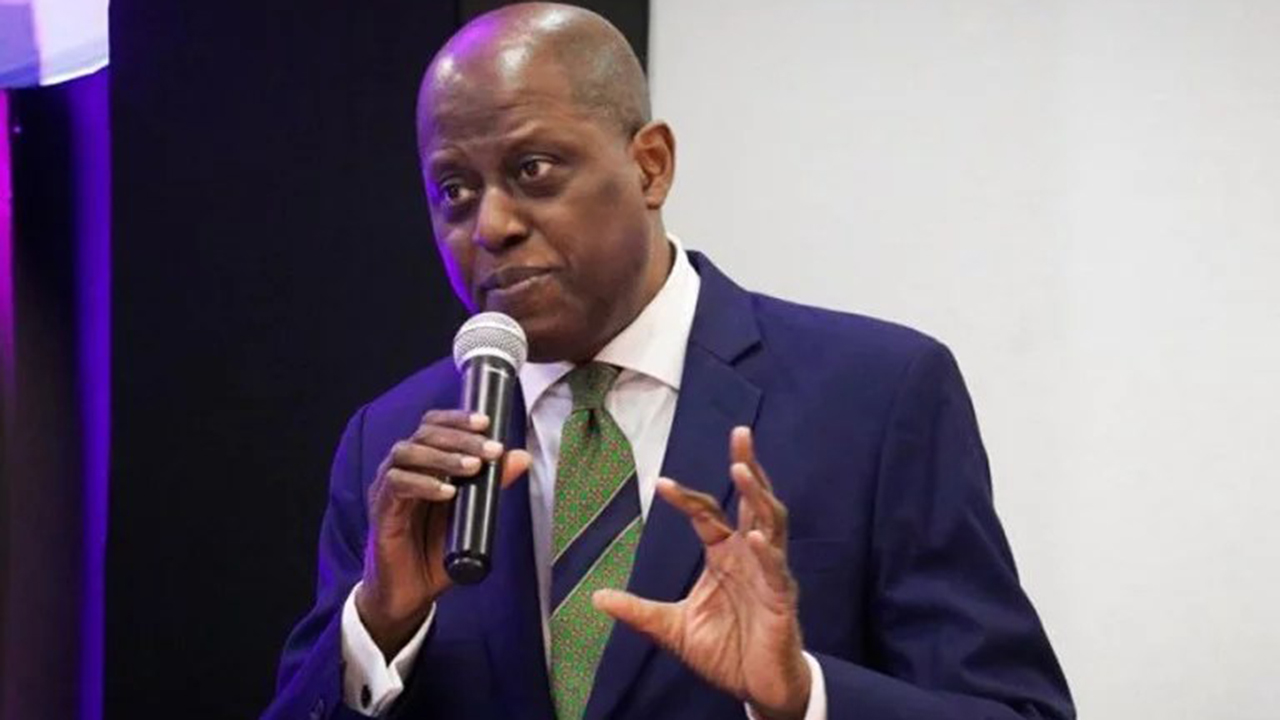
The Governor of the Central Bank of Nigeria (CBN), Olayemi Cardoso, has explained that the need to address weaknesses in monetary policy transmission, alongside improving economic conditions, informed the apex bank’s latest interest rate decision, which caught market participants off guard.
Speaking during a session titled How Central Banks Decide at the ongoing International Monetary Fund (IMF) and World Bank Annual Meetings in Bangkok, Thailand, Cardoso said Nigeria’s external reserves had reached their highest level in 18 years, inflation was consistently declining and economic growth remained at a reasonable pace. These developments, he said, created an opportunity for the CBN to correct existing imbalances.
Responding to a question from the IMF’s First Deputy Managing Director, Dan Katz, about how the CBN communicated a decision that surprised the market without causing significant disruption, Cardoso attributed the outcome to deliberate communication and reforms introduced before the announcement.
“You are absolutely right. It took the market by surprise, and markets, as we know, generally don’t like surprises,” he said.
Cardoso explained that several developments had strengthened the monetary policy framework ahead of the Monetary Policy Committee (MPC) meeting, particularly better coordination between fiscal and monetary authorities.
“We had signed up an MOU between the fiscal and the monetary to ensure that we were all on the same page, and that was very well received,” he said.
He also pointed to the introduction of the overnight financing rate, which he said offered greater clarity about prevailing interest rate conditions than the previous system.
“In terms of the situation from the macros, Nigeria was in a very good place. Our external reserves were the highest we had had in 18 years,” Cardoso said.
He added that sustained disinflation and steady economic growth provided an opportunity to address weaknesses in the transmission of monetary policy.
“These all put together a situation where we felt that we were in a relatively good place to do something we could have done earlier,” he said.
Nigeria’s different inflation cycle
Cardoso said Nigeria’s monetary policy decisions must be based on the country’s specific economic circumstances rather than simply mirror decisions taken by other central banks.
He explained that Nigeria’s inflation trajectory differed from that of many other economies because major domestic policy changes, including foreign exchange harmonisation and petrol subsidy removal, occurred at a different stage of the global inflation cycle.
“Our inflation cycle was pretty much different from much of the rest of the world, because we did certain things like the foreign exchange harmonisation, the lifting of subsidies at a different time in the inflation cycle of most of the countries,” he said.
“So inflation now came at that when many others were easing,” he added.
According to Cardoso, this difference means the MPC must independently assess domestic economic conditions instead of automatically following policy decisions in advanced economies.
Although MPC members monitor developments elsewhere, including in the United States, he said Nigeria’s policy choices must reflect its own economic realities.
“What is the United States doing? And everybody is looking at these things for different reasons,” he said.
He added that the institution’s leadership must keep deliberations focused on the issues most relevant to Nigeria at any given time.
How the MPC operates
Cardoso said the independence of MPC members was essential to encouraging thorough debate and preventing groupthink during monetary policy deliberations.
The committee has 12 members, comprising seven internal and five external members. He said the external members contribute independent viewpoints that strengthen discussions and challenge established assumptions.
According to him, the CBN deliberately appointed independent-minded external members during the transition from a currency crisis to economic stabilisation to enhance the credibility of its monetary policy decisions.
“By and large, they brought a completely different perspective from the perspective of those who are not just internal,” he said.
Cardoso said internal members were not expected to agree on conclusions with him before formal MPC meetings.
Instead, members received relevant data beforehand, allowing them to examine the information, request clarification from the committee’s secretariat and conduct scenario analyses before deciding on their positions.
“I don’t hold meetings with internals and come to a conclusion on the MPC meetings before we go there. I don’t do that,” he said.
He explained that effective leadership of the committee also involved identifying areas of agreement before addressing differences, helping to prevent discussions from becoming bogged down in disagreements over relatively minor issues.
He added that he reviewed members’ published personal statements to understand their reasoning, including after voting had concluded.
Communication and credibility
Cardoso said the CBN’s communication strategy played a significant role in helping market participants understand the reasons behind the unexpected decision.
He explained that he spent more time than usual engaging journalists after the MPC meeting to clarify the economic developments that had informed the decision.
Rather than merely announcing the policy action, he said, it was important to explain the challenges facing the economy, the reforms introduced and the progress made.
“I spent more time than normal in explaining where we were coming from and where we were, and it made it easier for them to understand why we took the decision,” he said.
Cardoso added that market participants were already familiar with the weaknesses in monetary policy transmission through their experience in the financial markets.
“They knew this because they operate in that market, and obviously knew that the action we are taking makes sense,” he said.
He stressed that the successful management of an unexpected policy decision depended on the credibility the CBN had built over time.
“To do such a thing successfully, you must have an element of credibility with the market,” he said.
“The market must have consistently seen you over a period of time doing things in the right way and believe they can put their trust in you,” he added.