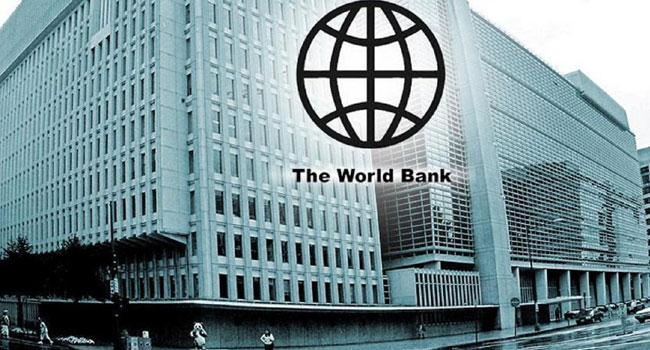
The World Bank has warned that developing countries could face a shortfall of 800 million jobs over the next 10 to 15 years, urging governments to accelerate investment and reforms to create employment opportunities for young people.
The President of the World Bank Group, Ajay Banga, gave the warning at the 2026 International Monetary Fund and World Bank Annual Meetings in Bangkok, Thailand.
Banga said about 1.2 billion young people in developing countries were expected to reach working age within the period, while only 400 million jobs were projected to be created.
He described the employment challenge as a defining economic concern and called on governments to work with private investors and development partners to expand opportunities and help young people secure productive livelihoods.
Banga said creating jobs required reliable electricity, efficient transport systems, digital connectivity, quality education and relevant skills. He also stressed the importance of predictable regulations and stronger institutions to encourage businesses to invest and expand.
The World Bank chief highlighted the role of small businesses and practical applications of artificial intelligence in improving productivity across agriculture, healthcare, education and other sectors.
He disclosed that the World Bank Group mobilised $112 billion in private capital in the last fiscal year, up from about $35 billion in the 2022 fiscal year, as part of efforts to expand development financing and support investments capable of generating jobs.
For Nigeria and other African countries with growing youth populations, the warning underscores the challenge of translating economic growth into productive employment, stronger businesses and improved living standards.
IMF warns of mounting global economic pressures
Meanwhile, the Managing Director of the International Monetary Fund, Kristalina Georgieva, has warned that rising public debt, energy supply disruptions and geopolitical tensions are placing increasing pressure on the global economy.
Georgieva said global economic growth was projected at 3.1 per cent in 2026, unchanged from the IMF’s forecast a year earlier.
She said the resilience of the global economy partly reflected increased investment in artificial intelligence, which was helping to offset the negative effects of energy shocks.
However, she cautioned that rising borrowing costs and high debt levels were limiting governments’ ability to respond to economic disruptions. Persistent inflation could also place further pressure on households and businesses.
The IMF chief urged countries with high debt levels to adopt credible medium-term fiscal plans, control inflation and strengthen their ability to withstand future economic shocks.
She also stressed the need to ensure that economic reforms protect vulnerable populations.
Georgieva warned that although artificial intelligence could boost productivity, it could also disrupt employment, raise financial stability concerns and expose countries to growing cybersecurity threats.
She called for urgent international cooperation to help countries prepare for AI-driven changes, strengthen financial systems and ensure that the benefits of emerging technologies were more widely shared.
The warnings from both institutions highlight the connection between economic stability, investment and job creation as developing countries face the challenge of managing financial pressures while providing opportunities for a rapidly growing workforce.
For Nigeria, the challenge extends beyond sustaining economic growth to creating conditions that enable businesses to expand, attract investment and provide meaningful employment for young people.